It can be challenging and unbearable to have debt. Lots of folks find several debts rather challenging. Every loan could have different conditions. Some obligations also have high interest. Others could have lower balances instead. Choosing the best approach is rather important. Two common techniques need to be noted. These strategies are the debt avalanche and snowball. Both approaches assist with debt freedom.
Smaller obligations could feel more manageable to overcome. With the proper approach, everything will be different. Mathematical savings are the emphasis of the avalanche. Snowball is all about psychological improvement. Both approaches could generate beneficial momentum. Your decision relies on your own circumstances. Knowing both approaches helps one to make decisions more easily.
An effective repayment plan depends on regularity. You have to keep up your consistent payments. These payments ought to be within your means. Additionally, under management, new debt ought to be avoided. Financial management is important for repayment at all times. Long-term success may depend on motivation.
What Is the Debt Avalanche Method?
The debt avalanche targets expensive debt first. You begin with your highest-interest debt. Keep minimum payments on other debts. Extra money goes toward costly debt. Once cleared, target the next debt. Continue until every debt disappears. This method follows a mathematical principle. High interest creates larger borrowing costs. Therefore, expensive debt receives immediate attention.
Suppose you have three different debts. One debt carries twenty per cent annual interest. Another debt carries fifteen percent interest. The final debt carries ten percent interest. Avalanche starts with the twenty-percent debt. After clearing it, target fifteen-percent debt. Then focus on the ten-percent debt. This order can reduce interest expenses. It can also lower total repayment costs.
What Is the Debt Snowball Method?
The snowball method starts with small balances. You first identify your smallest debt. Keep making minimum payments on remaining debts. This creates repeated repayment victories. Each victory can strengthen your motivation. Visible progress can make repayment easier.
Imagine having four different debts. Their balances may vary significantly. The smallest balance gets priority first. Interest rates receive less attention initially.
After clearing one balance, momentum grows. You then attack the next smallest balance. Eventually, every balance receives focused attention. This process creates visible financial progress. Seeing fewer debts can feel encouraging. The snowball method offers psychological benefits. Debt repayment can create constant mental pressure. Small victories can reduce that pressure.
Debt Avalanche vs. Debt Snowball
The biggest difference involves repayment order. Avalanche prioritizes interest rates first. Snowball prioritizes balances first. Both methods require minimum payments. Both methods also need extra payments. The main difference involves priority selection. This creates different financial outcomes. It also creates different emotional experiences. Understanding this difference helps your decision.
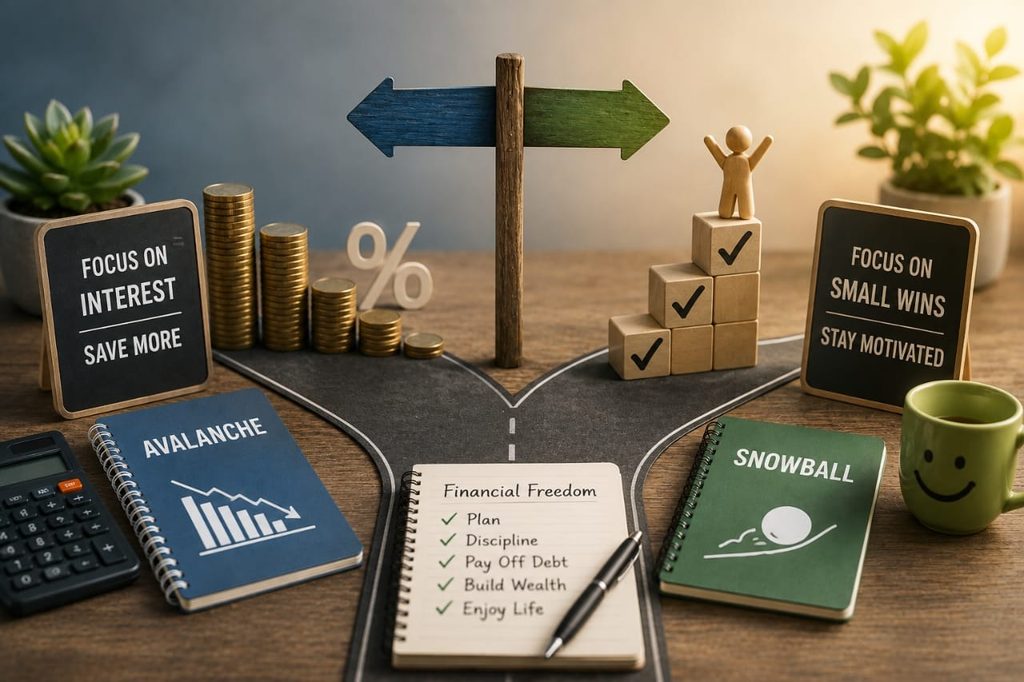
Avalanche usually provides better mathematical efficiency. It attacks expensive interest charges sooner. This can reduce overall interest costs. Snowball usually provides faster visible victories. Smaller debts disappear more quickly. This can improve motivation and commitment. Your personality should influence your decision. Your debt structure also deserves attention. Both factors can shape repayment success.
Why Avalanche Can Save More Money
Interest rates strongly affect repayment costs. Higher rates increase your total borrowing expense. This becomes important with larger balances. It also matters across longer repayment periods. Avalanche attacks expensive debts first. This can reduce accumulating interest charges. The savings can become significant over time. That makes Avalanche financially attractive.
Consider two similar repayment strategies. One targets high-interest debt first. Another targets small balances first. The first strategy may save more interest. Exact savings depend on circumstances. Your balances and rates both matter. Your monthly payment also affects outcomes. Therefore, compare your actual debt numbers. This creates a clearer repayment picture.
Why Snowball Can Build Motivation
Large balances may feel impossible initially. Small debts can feel easier to conquer. The snowball method uses this advantage. It creates an early repayment milestone. That milestone can encourage further action. Visible progress can strengthen commitment. Motivation becomes part of the strategy. Psychological wins can influence financial behaviour. Progress may otherwise feel invisible.
Clearing one account changes that feeling. You can immediately see fewer obligations. This can make repayment feel achievable. Confidence may encourage larger future payments. Snowball works well for many beginners. It creates simple and clear priorities. You focus on one debt initially. This reduces decision-making during repayment. That success can outweigh small interest differences.
Which Method Offers Better Results?
There is no universal winning method. Your financial situation determines the answer. Avalanche usually wins mathematically overall. Snowball can win behaviourally for some people. The best method encourages continued payments. You should consider your personal motivation. Your debt structure also matters significantly. Your repayment timeline matters too.
Avalanche may suit disciplined borrowers well. It rewards patience and financial optimization. You may save more interest overall. Snowball suits motivation-driven borrowers better. It provides faster emotional rewards. Both strategies can eliminate debt successfully. The difference often involves personal behaviour. Choose the strategy you can maintain.
How To Choose Your Repayment Strategy
Write everything clearly in one place. This creates a complete repayment picture. Then compare your available monthly payment. Identify how much extra money remains. That amount becomes your repayment weapon. A clear budget makes planning easier. Choose avalanche when interest savings matter. Choose Snowball when motivation matters more. Consider your past financial behaviour carefully.
Ask yourself how you stay motivated. Do quick wins keep you committed? Or do numbers drive your decisions? Your honest answer can guide you. There is no wrong choice. You should also consider debt size. Large balances may benefit from the avalanche. High rates can increase costs quickly. Small balances may benefit from the snowball method. Common Mistakes During Debt Repayment
Using Extra Income For Debt
Extra income can accelerate debt repayment. Bonuses can become useful repayment opportunities. Freelance income can also help significantly. Tax refunds may provide another opportunity. Avoid spending every unexpected payment immediately. Consider directing some money toward debt. This can shorten your repayment timeline. It can also reduce future interest costs. You can create a separate repayment fund.
However, avoid ignoring essential financial needs. Maintain necessary expenses before extra payments. Emergency savings may also deserve attention. Balance remains important during repayment planning. Extra income works with both methods. Avalanche directs extra money toward costly debt. Snowball directs extra money toward small debt. The choice depends on your chosen strategy.
Can You Use Both Methods Together?
Some borrowers prefer a blended approach. This combines psychological and mathematical benefits. You might clear one tiny debt. Then switch toward high-interest debt. This creates an early psychological victory. Later, prioritize expensive remaining balances. The approach provides flexibility during repayment. However, consistency remains essential throughout.
Another option involves using interest thresholds.
You could prioritize extremely expensive debts. Then target smaller balances afterward. This requires understanding your debt structure. Compare rates and balances carefully. A repayment calculator can simplify comparisons. Your goal remains reducing total debt. The strategy should support that goal. The best approach feels manageable. Debt repayment should fit your actual life. Do not choose unnecessary complexity. Simple plans are easier to follow.
Debt Repayment And Long-Term Financial Freedom
Paying debt is only one financial step. You should also build stronger money habits. Build savings alongside long-term repayment. Debt freedom becomes easier with preparation. Once debts disappear, redirect those payments. Do not immediately increase lifestyle spending. Instead, build emergency savings first. Then consider long-term financial goals. Investing may become another future priority.
Saving for major purchases can help. Financial freedom requires continued discipline. Debt repayment is only the beginning. Small financial choices create lasting results. Every payment reduces your outstanding balance. Every avoided debt improves future flexibility. Every saved dollar creates more options. Your strategy should support these outcomes. Whether avalanche or snowball works best, act.
Conclusion
Repayment of debt calls for a realistic and straightforward approach. Both approaches might assist one in lowering debt. The avalanche approach helps one to pay more interest. It focuses on obligations with higher interest rates. This method has more mathematical advantages. The snowball approach works differently. It starts with the smallest balances first. Little successes can inspire great drive. These victories inspire ongoing repayment initiatives. For everyone, neither approach is ideal. Your decisions should be informed by your financial behaviours.
Think about your incentive before deciding on an approach. Think about your rates of interest too. Pick a plan you could follow all of the time. Try not to change techniques without a good cause. Regularity is more important than precise computations. Every payment gets you one step toward freedom. Follow your development over the repayment trip. Celebrate achievements without adding to your debt. Keep concentrated should development seem sluggish.
FAQs
The Debt Avalanche Method: What Is It?
The avalanche strategy gives first focus to high-interest loans. On any outstanding obligations, you make minimum payments. Extra money helps you with your most expensive debt.
Which approach helps one to save more money?
Usually, the avalanche approach helps one to save more money. It addresses high-interest debt before lower amounts. This cuts costly interest early. However, your debts determine the outcome.
Which Approach Is Superior for Motivation?
Often the snowball approach offers more motivation. Smaller obligations get paid off rather fast. Every win helps one to clearly repay their debts. This might help one keep their financial discipline.
Can I Use Both Approaches to Debt?
Yes, you can use both approaches together. Some folks would rather use a hybrid approach. One minor obligation you could solve. After that, address your debt with the highest interest.
Should I pay minimums on every obligation?
Yes, minimum payments ought to stay regular. Not making payments might lead to more economic issues. Always cover your necessary monthly payments. Then manage additional funds deliberately.