Managing money feels harder than ever. Everyday costs continue rising quickly. Bills consume more income than before. Saving money also requires stronger financial discipline. Many people need simple budgeting methods. It divides income into three categories. These categories include needs, wants, and savings. This approach makes money management easier.
But can this rule still work? Modern expenses have changed significantly in recent years. Housing costs can consume most monthly income. Food prices have also increased steadily. Transportation expenses create additional financial pressure. Young workers face unique financial challenges. Their incomes may remain relatively limited. Their financial goals may also differ. Therefore, traditional budgeting rules need flexibility.
The 50/30/20 rule remains useful today. However, it should not become rigid. Everyone has different financial responsibilities. Income levels also vary between households. Personal priorities can change throughout life. A flexible budget can provide better results. The rule offers a helpful starting point. Smart adjustments can make it more practical.
What Is the 50/30/20 Budget Rule?
The 50/30/20 formula involves splitting monthly income into three categories. Half of your income will go to necessities. Thirty percent of your income will go to your wants. Twenty percent will go towards your financial goals. Financial goals may include savings, investments, and debt repayment, among other things. Necessities include expenditures that you have to pay in order to live. They may include your rent and utilities. Groceries normally fall into this category.
Travelling expenses could be categorised as necessities as well. Healthcare costs could be considered necessities as well. Wants include optional expenditures. The rule gained popularity due to its simplicity. People may find it difficult to deal with complex financial arrangements. Sometimes, simple rules could foster good financial practices. Percentages offer you guidelines when making decisions on how to spend
Why Did The 50/30/20 Rule Become Popular?
The rule became popular through simple budgeting advice. Many people wanted straightforward money management. Complex financial plans can feel overwhelming. The rule removes much unnecessary complexity. It provides three understandable spending categories. These categories make financial decisions easier. The method also encourages balanced financial behaviour. People need money for current living costs.
The rule recognises all three priorities. This balance makes budgeting feel more realistic. Strict saving plans can sometimes become unsustainable. Another advantage involves financial awareness. Tracking categories reveals spending patterns. People may discover unnecessary monthly expenses. They may also identify weak saving habits. This information can support better financial decisions. For beginners, that awareness becomes extremely valuable.
Does the rule still work today?
The basic principle still works today. However, the percentages may require adjustment. Modern living costs differ between individuals. Housing expenses demonstrate this problem clearly. Rent can consume more than half of income. This happens especially within expensive cities. Income differences also affect budgeting percentages. Someone earning more has greater flexibility.
Forcing strict percentages could create unnecessary stress. Budgeting should reflect actual financial circumstances. The rule works best as guidance. It should not become an absolute requirement. Your income should determine practical spending limits. Your responsibilities should influence financial priorities. Your goals should also shape your budget. Flexibility makes this approach more sustainable.
Rising Living Costs Change Budget Priorities
Living costs have increased across many categories. Housing remains a major financial burden. Groceries can also consume larger portions of incomes. Transportation expenses continue affecting household budgets. Utility bills may also increase monthly pressure. These changes make traditional percentages harder to use. A temporary imbalance can remain perfectly reasonable.
Essential expenses may exceed fifty percent easily. This creates problems for many households. People may have less money available. Their wants category can become much smaller. Savings may also require temporary reductions. This situation does not mean failure. Instead, budgets should reflect current realities. People can adjust percentages when necessary.
How to Adjust The Rule For Your Income
People with lower incomes need flexibility. Their essential expenses may dominate monthly income. They might use a different percentage structure. For example, needs could reach sixty percent. Wants could receive twenty percent instead. Savings could receive the remaining twenty percent. Higher earners may have different opportunities. They can potentially increase their savings rate.
This allows stronger investment contributions. They can also accelerate debt repayment. Financial goals may become easier to achieve. The important point involves personal circumstances. No single percentage works for everyone. Your budget should match your actual income. It should also match your financial obligations. Reviewing your budget regularly remains important.
Can the rule help with debt?
Management of debts also fits well here. Some of the debts may be considered part of necessary expenditures, but others may need further financial consideration. Debts that earn high interest rates will need to be repaid seriously. For instance, credit card debts may be quite expensive. This is because repaying debts earning high interest could be a financially rewarding move.
Emergency funds may still have to be considered. Emergencies may otherwise cause borrowing. Goals of becoming debt-free should also be practical and measurable. The amount for debt repayment should be set and monitored every month. Milestones should be celebrated while achieving this goal.
How Should Savings Fit Into The Rule?
This includes financial targets under the category of twenty percent. This fund acts as a defence mechanism against any unforeseen costs. It may be used for repairs or in case of income loss. Creating an emergency fund will give individuals financial space. Other savings may be aimed at certain plans. One of the savings plans that matters to most employees is retirement savings.
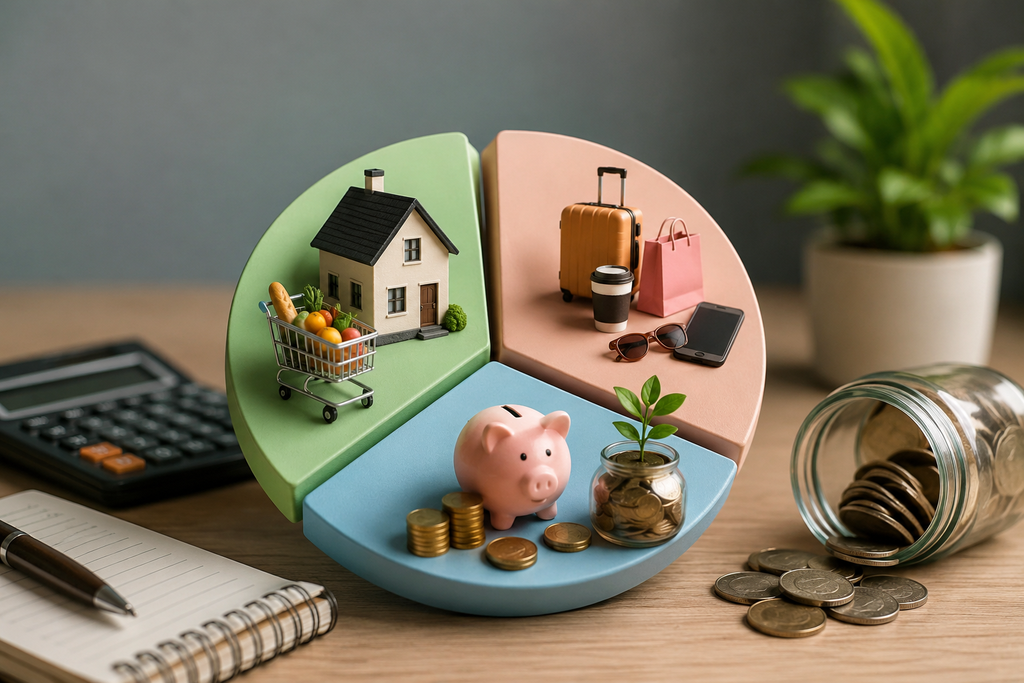
Investment can help in building wealth over time. Education savings may also be a factor. Notwithstanding, twenty percent may not be compulsory for all. Some individuals may save much higher amounts. Some may also find themselves saving smaller amounts. What is important is consistent saving over time. The emergency fund takes precedence.
Should Wants Really Receive Thirty Percent?
Wants enable people to enjoy themselves. Wants can never be stripped away completely since they will lower motivation. Sometimes people require some entertainment and relaxation. People can indulge in wantful spending and still maintain balance. But it is essential to keep wants within certain limits. Problems occur when wants are out of control.
Unnecessary subscriptions can lead to additional expenses every month. Spending on restaurants can lead to extra expenses. Checking for wants can identify areas where one can save some money. You can cancel subscription services that you do not use. Lower your shopping rate. Look for cheap entertainment options when you can.
Common Mistakes When Using This Rule
One common mistake involves ignoring actual expenses. People sometimes follow percentages blindly. This can create unrealistic monthly budgets. Your real expenses should always come first. Percentages should support your financial situation. Another mistake involves confusing needs and wants. Some expenses may seem essential initially.
Premium subscriptions often represent optional spending. Expensive dining can also become discretionary. Understanding categories improves budgeting accuracy. People also forget irregular annual expenses. Insurance payments may arrive once yearly. Vehicle repairs can happen unexpectedly. School expenses may also appear suddenly. These costs should receive monthly planning.
How To Make The Rule More Practical
Start by calculating your monthly take-home income. Then list every regular monthly expense. Separate essential costs from optional spending. Include savings within your financial plan. Track everything for several months. Next, compare your actual spending percentages. Identify categories causing financial pressure. Look for areas requiring reasonable adjustments.
You can also create realistic spending targets. These targets should reflect your circumstances. Review them after major financial changes. Income increases may allow stronger savings. New responsibilities may require different priorities. Using practical personal budgeting methods helps. A simple spreadsheet can track monthly expenses. Budgeting apps can provide automatic spending summaries.
Conclusion
Many people struggle with managing monthly income. This rule makes financial planning easier. It separates needs, wants, and savings. However, modern living costs create challenges. Housing expenses can exceed traditional budget limits. Food and transportation costs also keep increasing. Therefore, following exact percentages is unnecessary. Your financial situation should guide your decisions. A flexible budget can work more effectively. It can also reduce unnecessary financial stress
The main goal is building better money habits. You should understand where your money goes. Then, you can make smarter spending choices. Small improvements can create meaningful financial progress. The rule should work around your circumstances. It should never make budgeting feel impossible. Lower-income households may need different percentages. Higher earners may save significantly more money. People with debt need special financial priorities.
FAQs
1. What is the 50/30/20 rule?
The rule divides income into three categories. Fifty percent covers essential living expenses. Thirty percent covers personal wants. Twenty percent supports savings and financial goals.
2. What counts as a financial need?
Needs include essential living expenses. These include housing, food, and utilities. Transportation and healthcare may also qualify.
3. What counts as a financial want?
Wants include optional lifestyle expenses. Examples include shopping and entertainment. Dining out can also fall into wants.
4. Is twenty percent savings necessary?
Twenty percent is only a guideline. Some people can save more monthly. Others may need to save less temporarily.
5. Is this rule good for beginners?
Yes, it provides a simple starting point. Beginners can easily understand its structure. They can adjust it as needed.